Learning from DeFi: Would Automated
Market Makers Improve Equity Trading?
Katya Malinova and Andreas Park
Some Motivation
- Blockchain: borderless general purpose value and resource management tool
Basic Idea
- DeFi: financial applications that run on blockchains
- \(\Rightarrow\) brought new ideas and tools
- one new market institution: automated market makers
Application: decentralized trading with automated market makers

Key Components
- Our question:
- Can an economically viable AMM be designed for current equity markets?
- Would such an AMM improve current markets?
- pooling of liquidity
- pro-rated
- fee income
- risk
- Liquidity providers:
- use existing assets to earn passive income
- Liquidity demanders:
- predicatable price
- continuous trading
- ample liquidity
Liquidity Supply and Demand in an Automated Market Maker
Constant Liquidity (Product) AMM
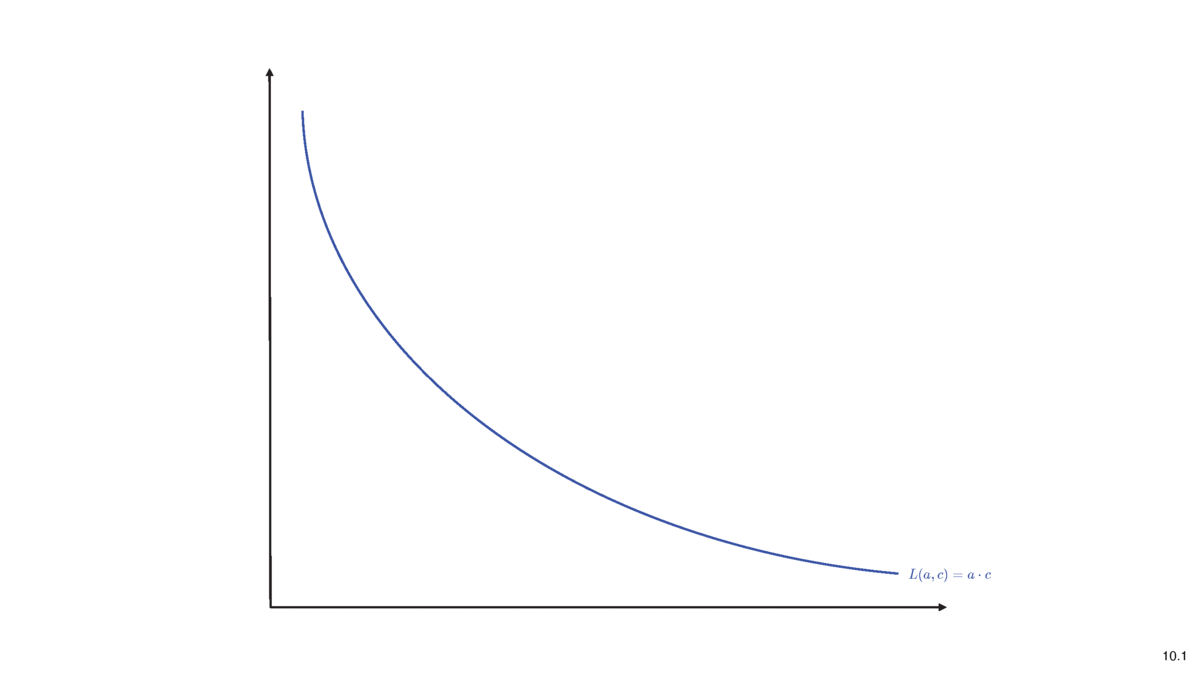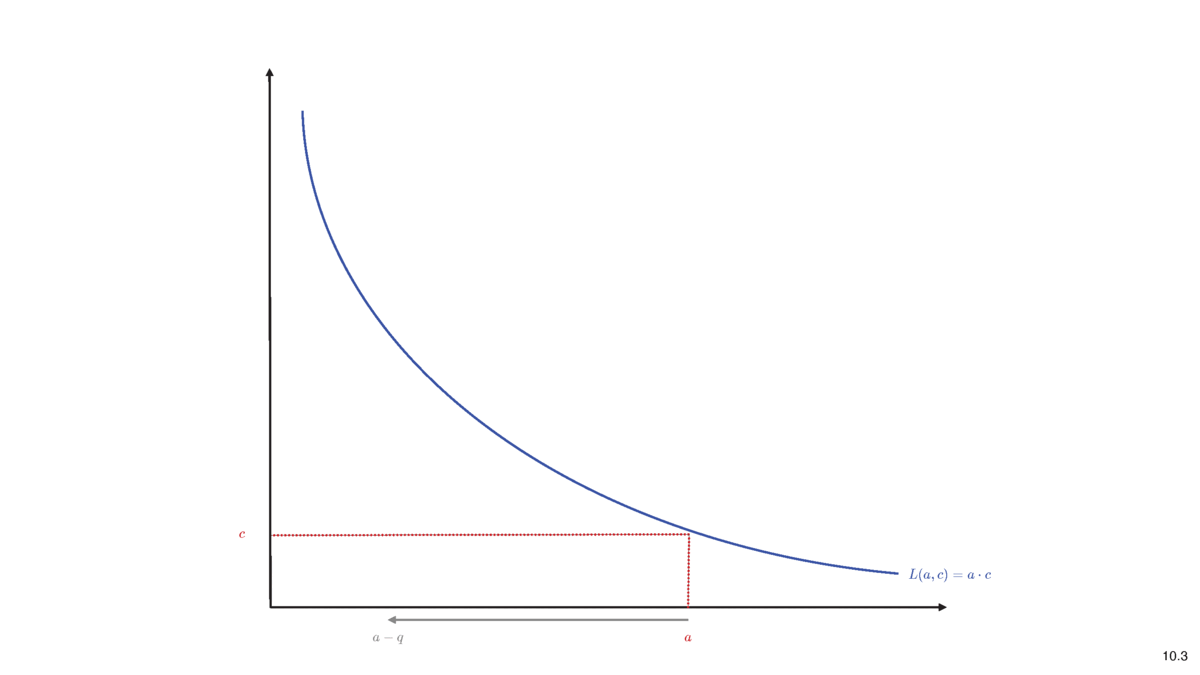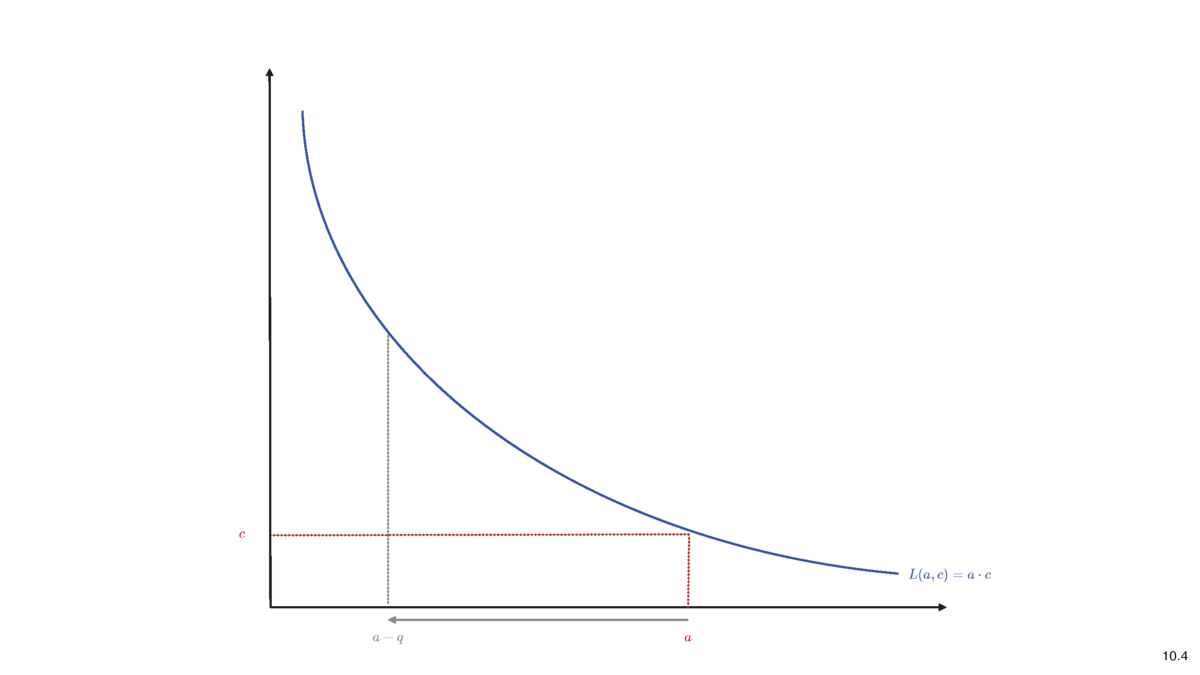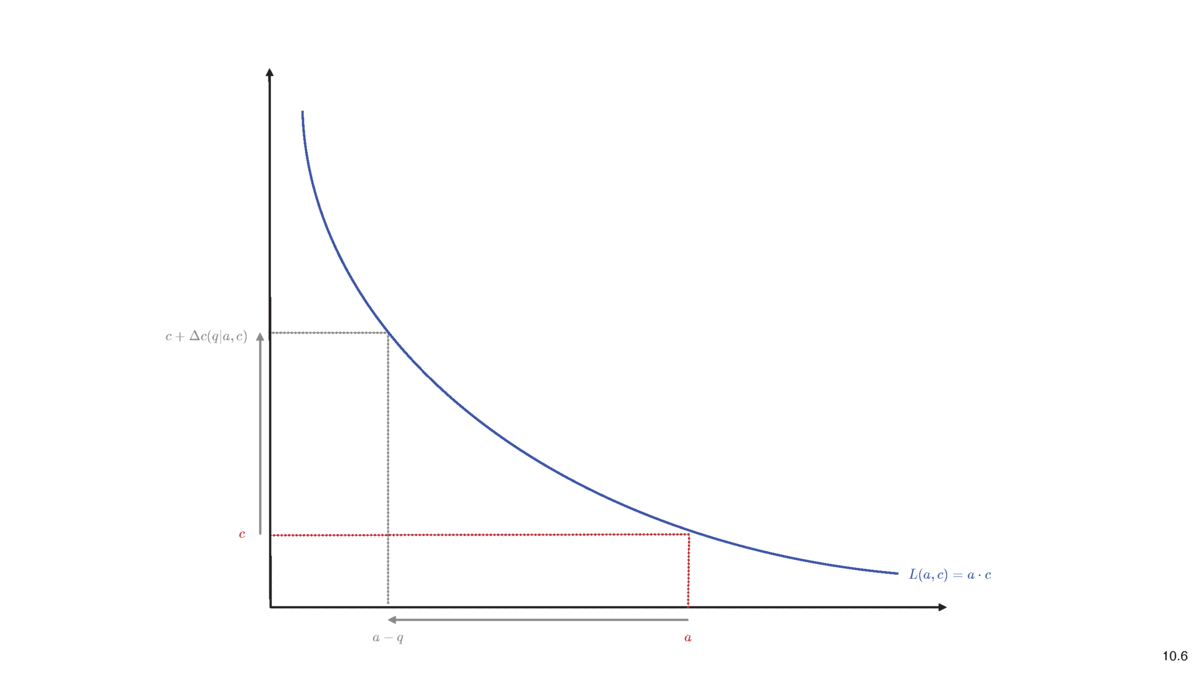
- Purchase \(q\) of asset
- Deposit cash \(\Delta c (q)\) into liquidity pool, extract \(q\) of shares
- Idea of pricing: liquidity before trade \(=\) after trade
\[L(a,c)=L(a-q,c+\Delta c)\]
- AMMs require liquidity deposits
- Deposits:
- \(a\) units of an asset (e.g. a stock)
- \(c\) units of cash
The Pricing Function
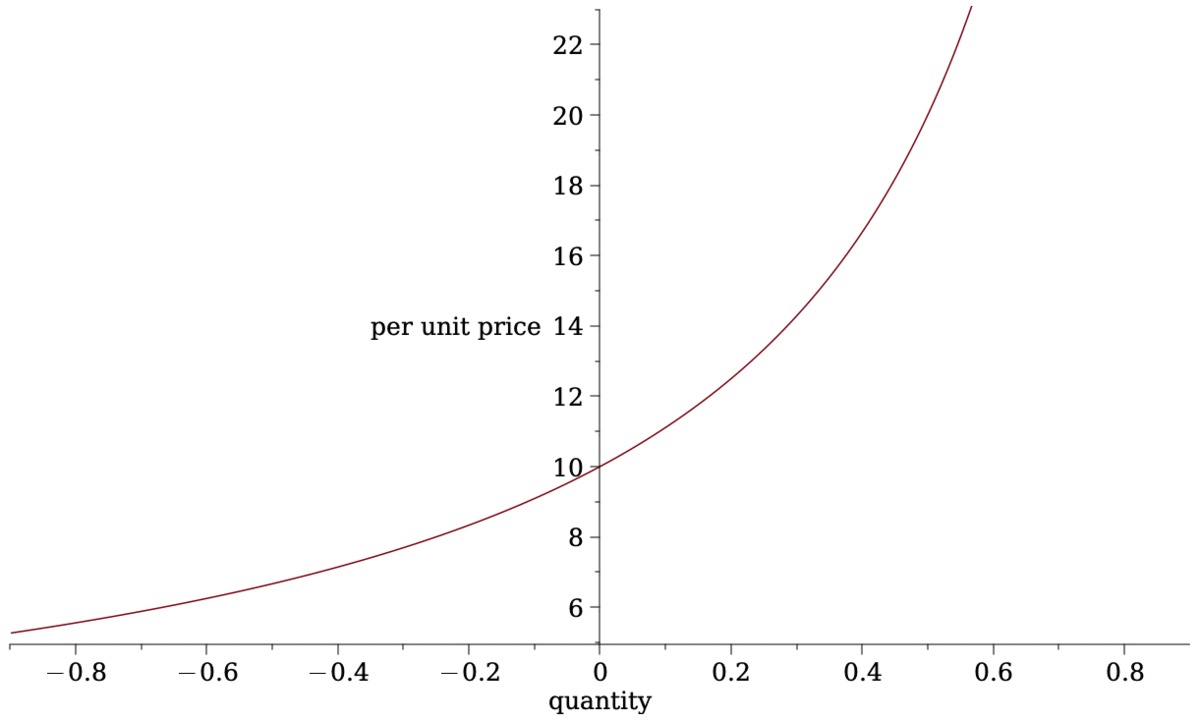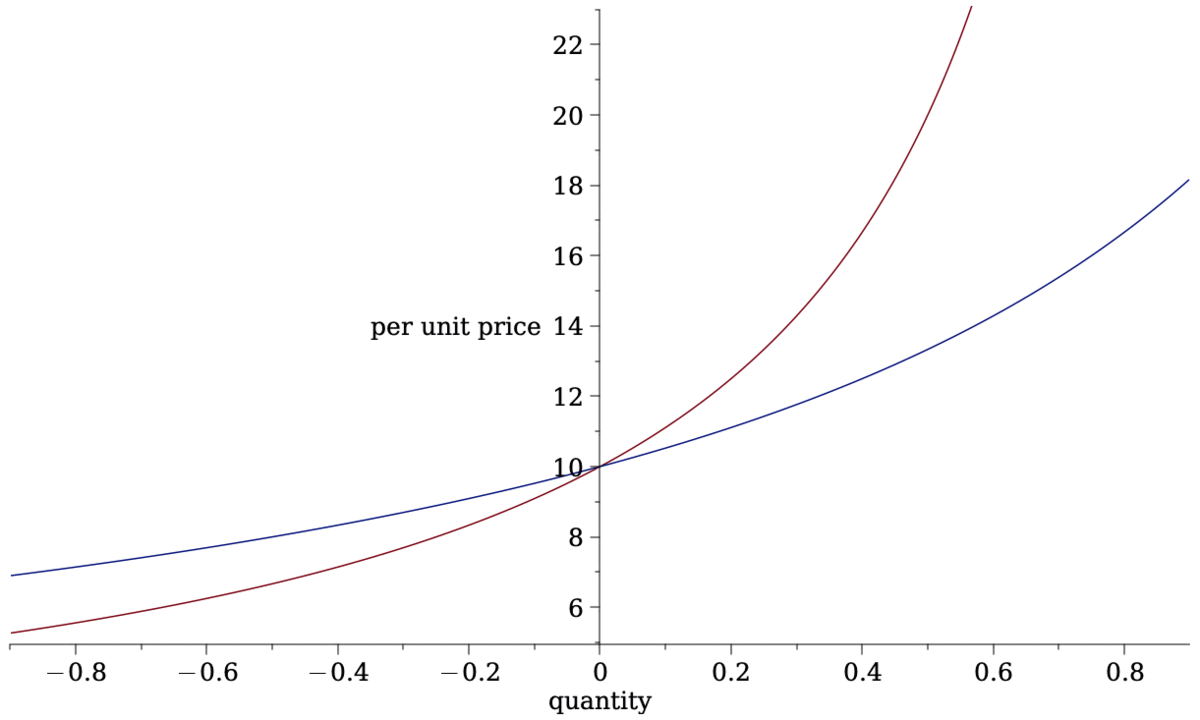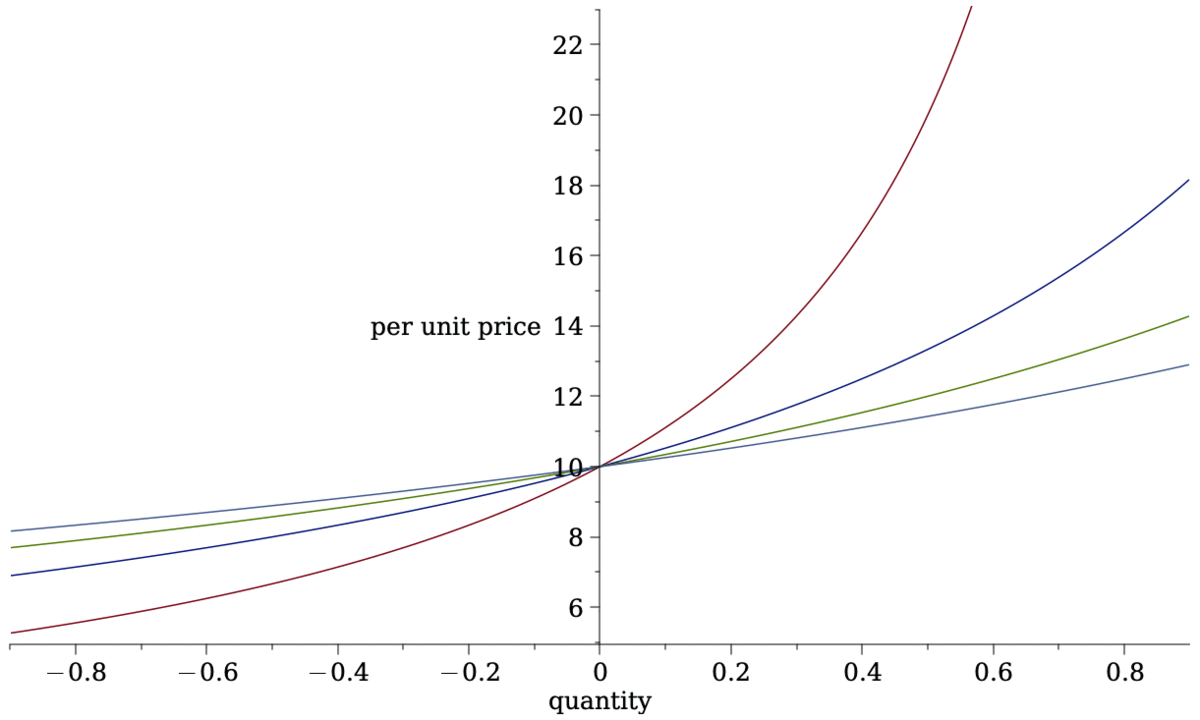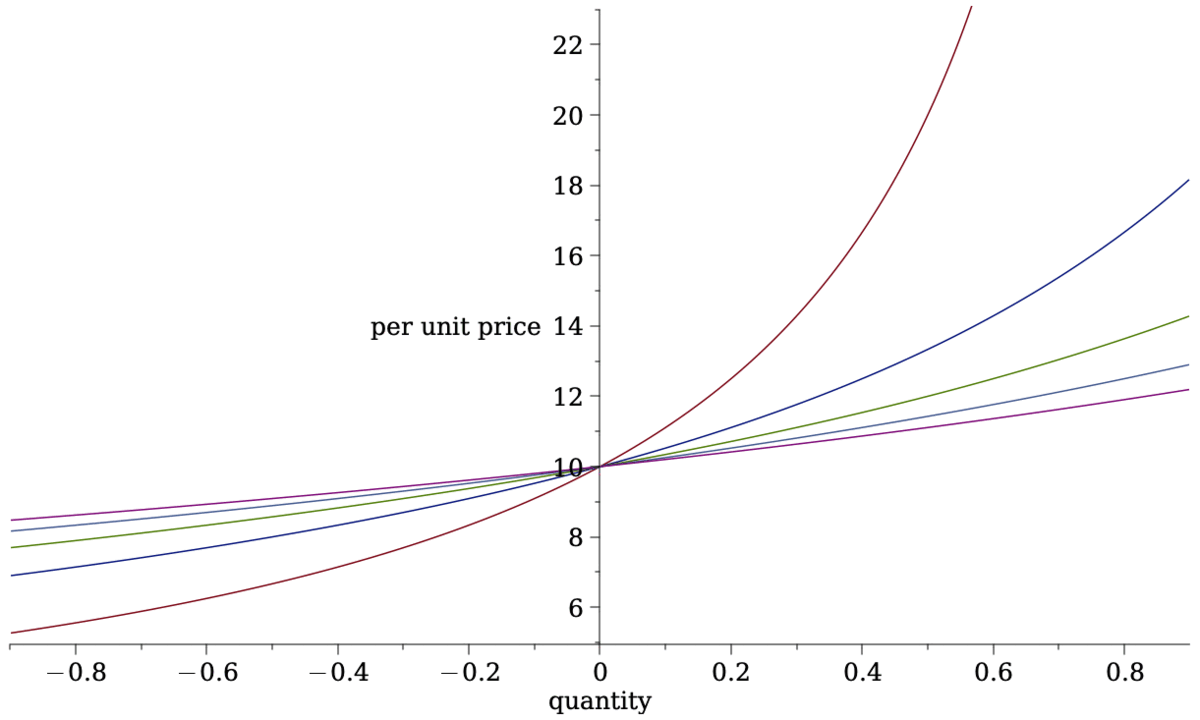
- Most common form of AMM liquidity rule is Constant Product Pricing
\[L(a,c)=a\cdot c~\Rightarrow~a\cdot c= (a-q)\cdot (c+\Delta c).\] - Total cost of trading \(q\) \[\Delta c=\frac{cq}{a-q}.\]
- Price per unit \[p(q)=\frac{c}{a-q}.\]
- Average spread paid\[\frac{p(q)}{p(0)}-1=\frac{q}{a-q}.\]
- liquidity provider makes asset and cash deposit
- more deposits flatten price curve
- may attract more volume
- but larger "positional" dollar loss when prices move
- larger liquidity deposits \(a\) \(\Rightarrow\)
- lower costs (price impact) for liquidity demanders
Basics of Liquidity Provision in an AMM for a Model
- fundamental value changes
- \(\Rightarrow\) informed arbitrageur
- \(\Rightarrow\) LP incur losses (trade at the "wrong price")
- \(\Rightarrow\) informed arbitrageur
- a liquidity trade
- arbitrageurs (eventually) trade back to the original price
- \(\to\) liquidity deposits return to the original values \((a, c)\)
- losses on informed
- no gains (nor losses) on noise
Basics of Liquidity Provision
\[E[\text{positional loss}(R)]+F\cdot E[\text{another function of }R]+F\cdot \frac{\text{dollar volume}}{\text{initial deposit}}\ge 0.\]
\[\text{LP payoff}=\text{what I sold it for}-\text{value of net position}+\text{fee income} \ge 0 \]
- Characterize liquidity provision for stocks as a
"collective" deposit \(\alpha\) of firm's market cap- initial deposit \(\alpha \nearrow \) \(\Rightarrow\) LP payoff \(\searrow\)
-
Competitive liquidity provision \(\Rightarrow\) initial deposit fraction \(\bar{\alpha}\) such that LPs break-even, as a function of
- balanced $-volume
- asset volatility/return \(R\) distribution
- fee \(F\)
Sidebar: we can quantify how much a PASSIVE LP loses when the price moves by \(R\)
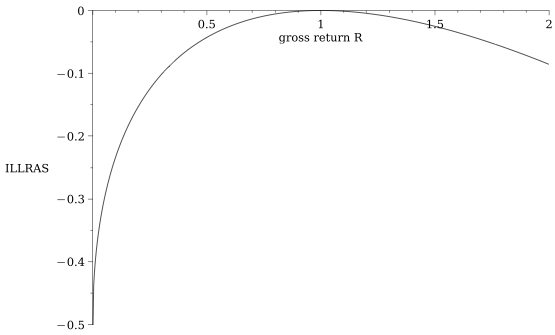
for orientation:
- If the stock price drops by 10% the incremental loss for liquidity providers is 13 basis points on their deposit
- \(\to\) total loss=-10.13%
- If the stock price rises by 10%, the liquidity provider gains 12 basis points less on the deposit
- \(\to\) total gain =9.88%
\[\frac{\text{adverse selection loss when the return is \(R\)}}{\text{initial deposit}}=\sqrt{R}-\frac{1}{2}(R+1)\equiv \textit{ILLRAS}(R)\]
as in Barbon & Ranaldo (2022)
"Incremental Loss from Long-Run Adverse Selection"
- Wants to trade some quantity \(q\).
- Is better off with AMM relative to traditional market if
\[\text{bid-ask spread}\ge\text{AMM price impact} +\text{AMM fee}.\]
- two opposing forces for \(F\nearrow\) for liquidity demand
- more liquidity provision
\(\to\) lower price impact - more fees to pay
- more liquidity provision
- Finding: There is an optimal fee:
\[F^\pi=\frac{1}{E[|\sqrt{R}-1|/2]+V}\left(-2q\ E[\text{ILLRAS}]+ \sqrt{-2qV\ E[\text{ILLRAS}]}\right).\]
Liquidity Demander's Decision & (optimal) AMM Fees
Model Summary
- Have:
- equilibrium choices for competitive liquidity provision
- fee that minimizes liquidity demander AMM costs (\(>0\))
- Next:
- Calibrate to stock markets
- AMM Feasible?
- AMM costs at the optimal fee < bid-ask spread?
- is the max (break-even) supplied liquidity enough?
- AMM costs at the optimal fee < bid-ask spread?
How we think of the Implementation of an AMM for our Empirical Analysis
Approach: daily AMM deposits
- AMMs close overnight.
- Market: opening auction \(\to\) \(p_0\)
- Determine: optimal fee; submit liquidity \(a,c\)
at ratio \(p_0=a/c\) until break even \(\alpha=\overline{\alpha}\)
- Liquidity locked for day
- At EOD release deposits and fees
- Back to 1.
Background on Data
Special Consideration 1: What volume?
-
some volume may be intermediated
- with AMMs: no need for intermediation
- \(\to\) intermediate volume should disappear
- \(\to\) use volume/2
Special Consideration 2: What's \(q\) (the representative order size)?
- use average per day
- take long-run average + 2 std of daily averages
- (also avg \(\times 2\),\(\times 4\), depth)
All displayed data CRSP \(\cap\) TAQ
- CRSP for shares outstanding
- WRDS computed TAQ statistics for
- quoted spreads (results similar for effective)
- volume
- open-to-close returns
- average trade sizes, VWAP
- Time horizon: 2014 - March 2022
- Exclude "tick pilot" period (Oct 2016-Oct 2018)
- All common stocks (not ETFs) (~7550).
- Explicitly not cutting by price or size
- All "boundless" numbers are winsorized at 99%.
Special Consideration 3:
Where to get expected returns and volume?
- Approach 1: "ad hoc"
- "one-day-back" look
- take yesterday's return and volume when deciding on liquidity provision in AMM
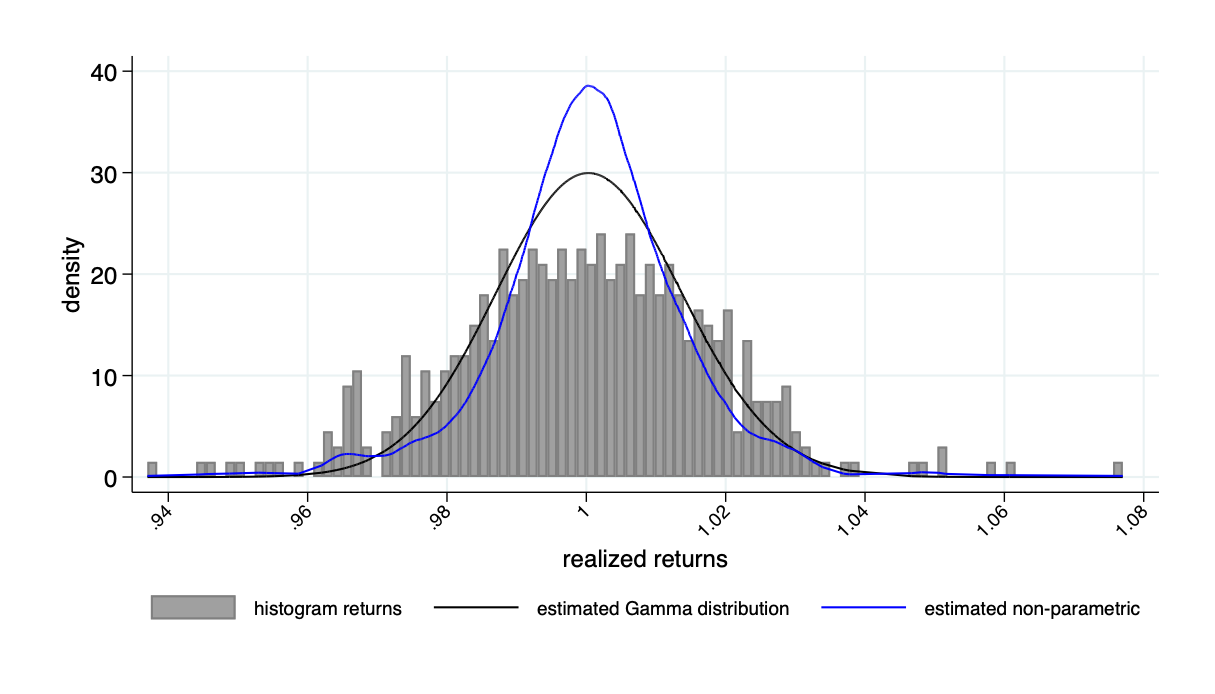
- Approach 2: estimate historical return distribution
AMMs based on historical returns
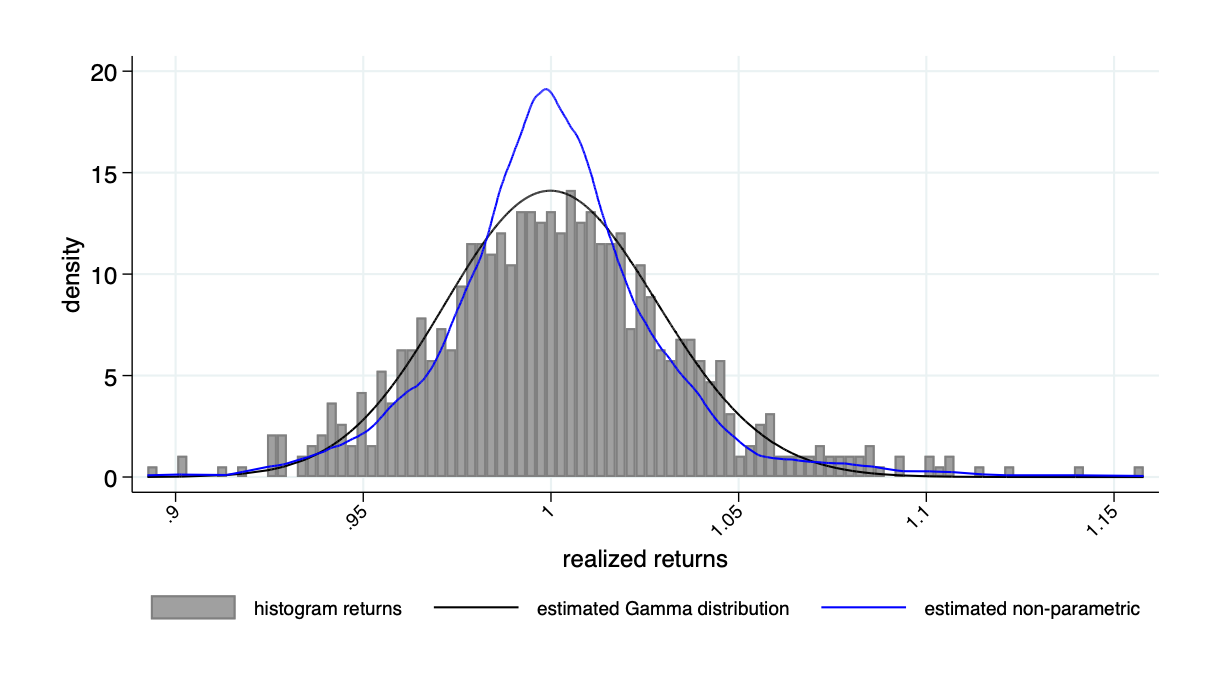
Return distribution example: Microsoft
Return distribution example: Tesla
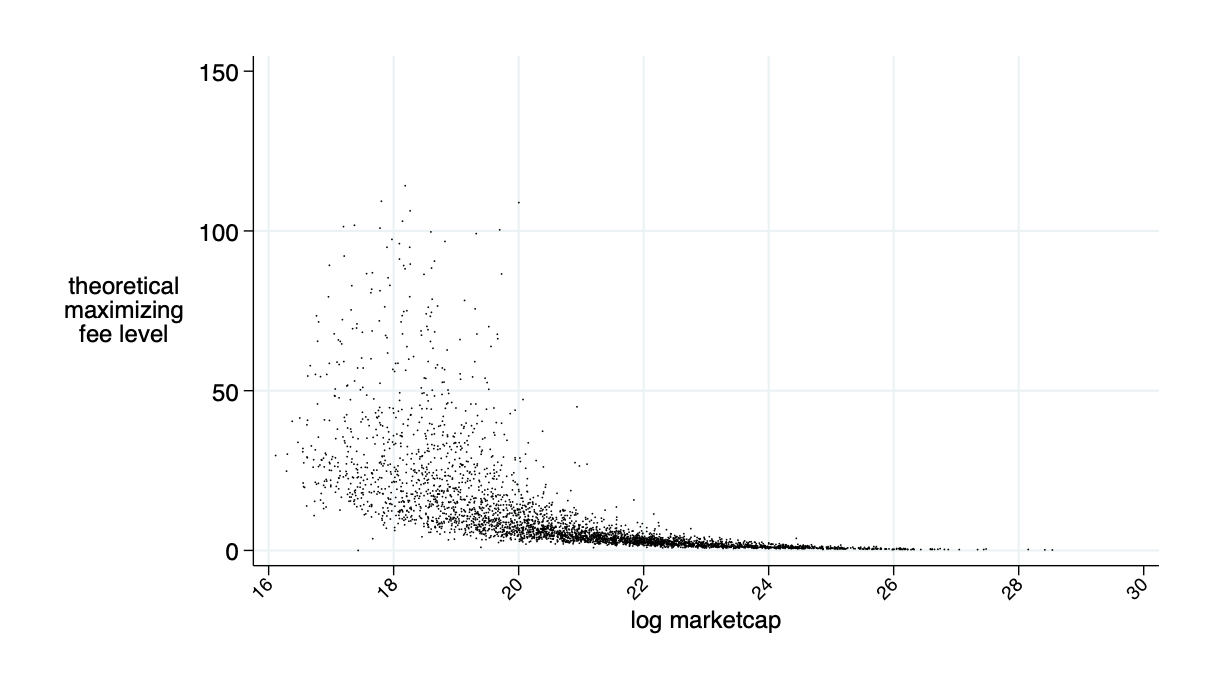
- average \(F^\pi=11\)bps
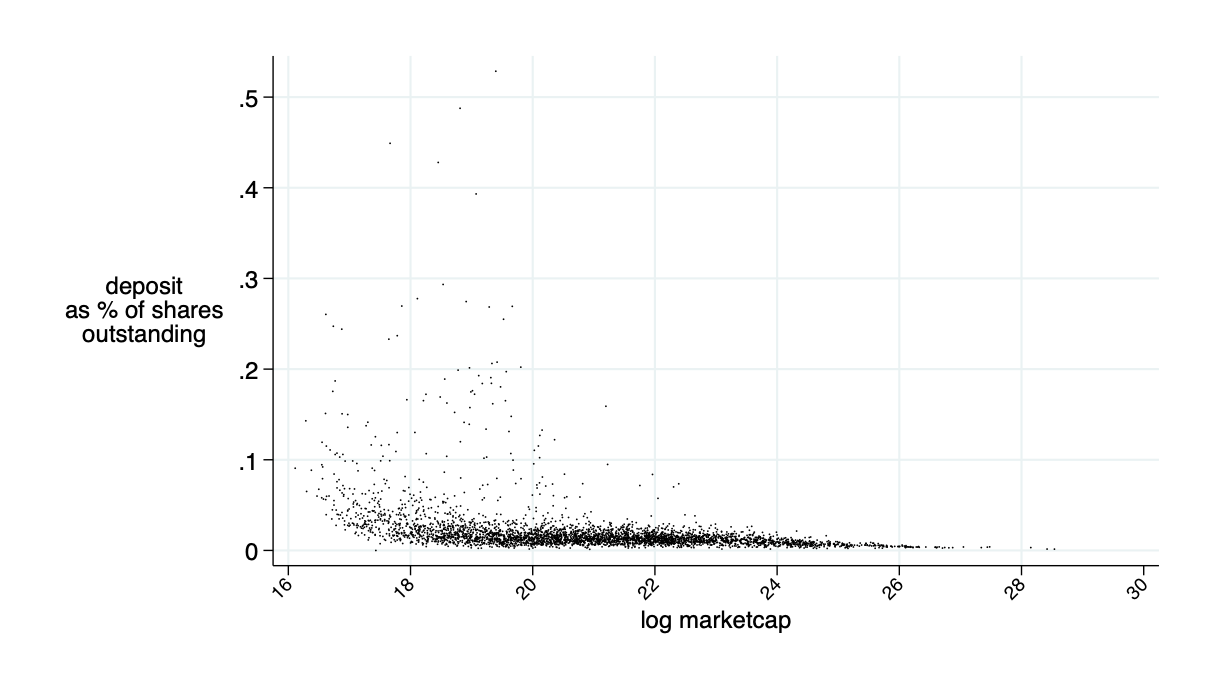
\(\bar{\alpha}\approx 2\%\)
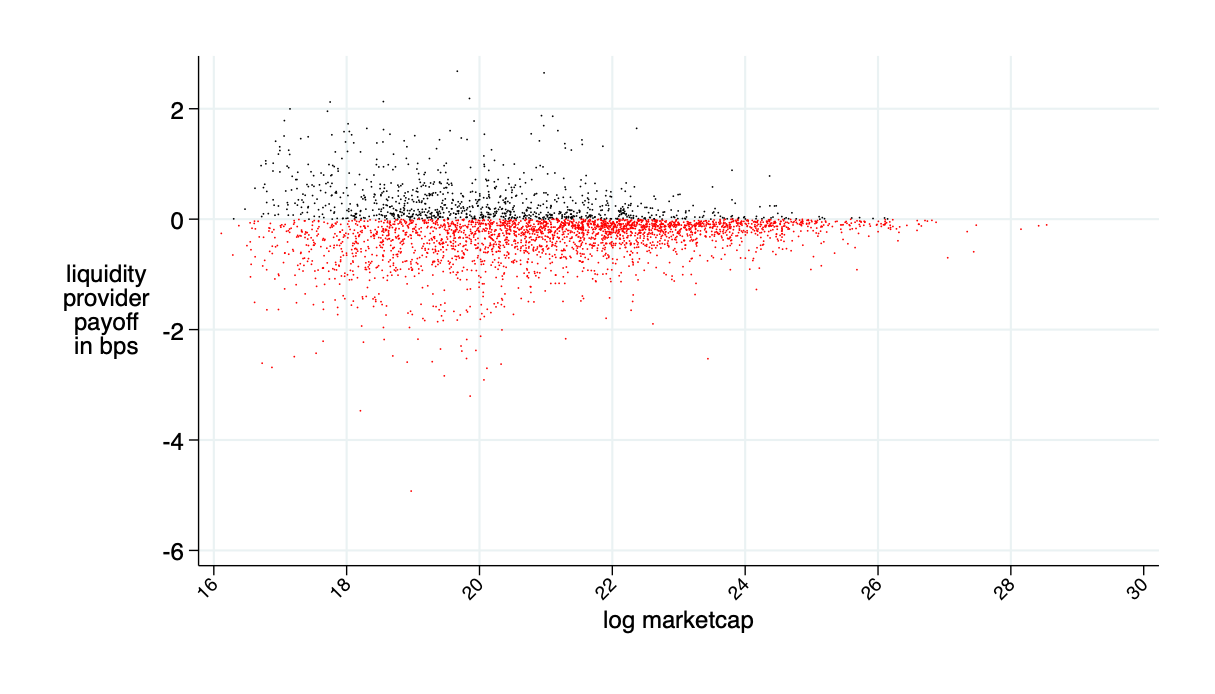
almost break even on average (average loss 0.2bps \(\approx0\))
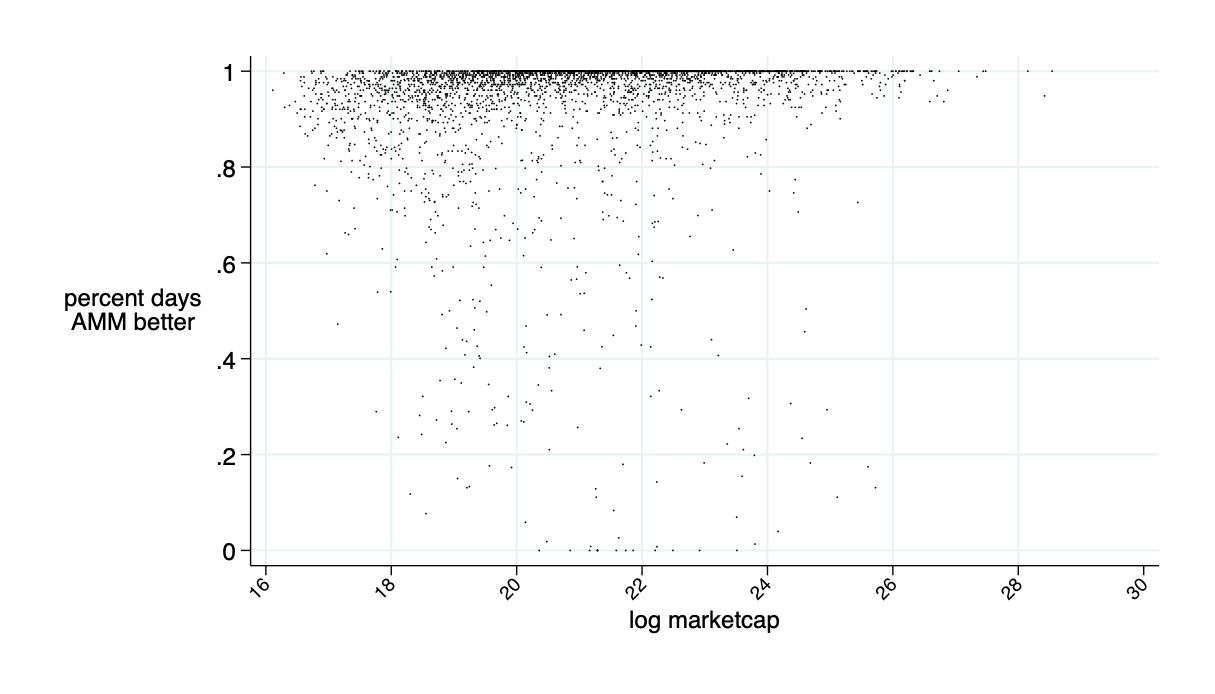
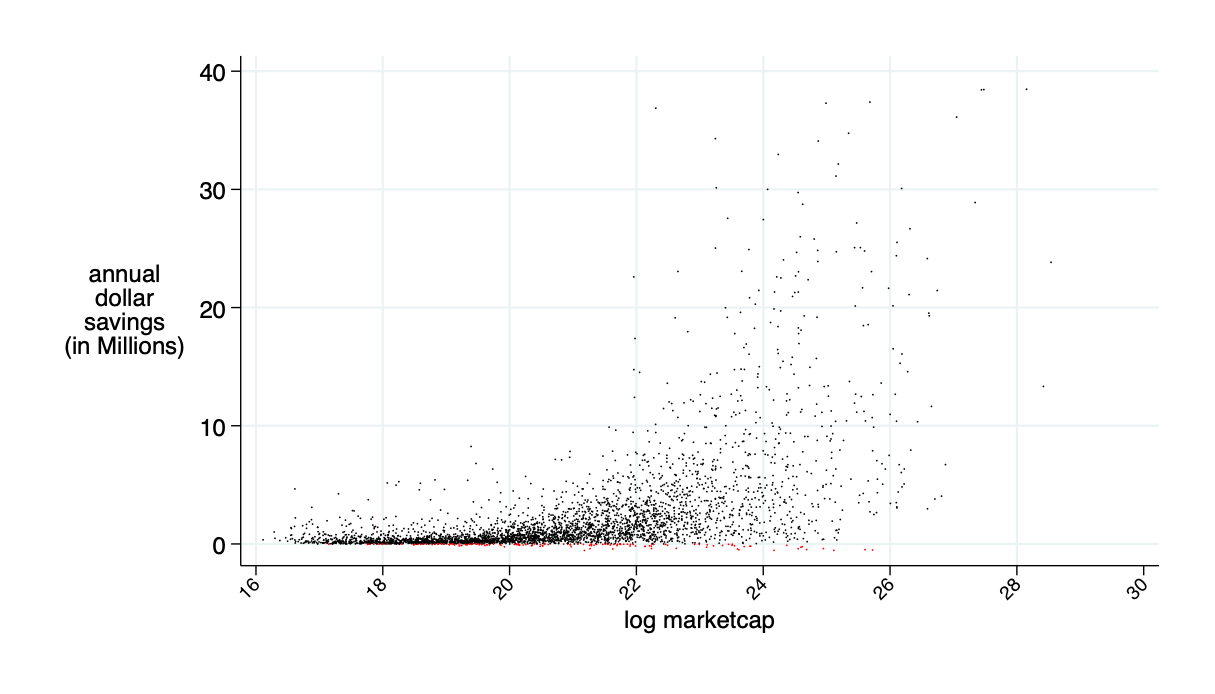
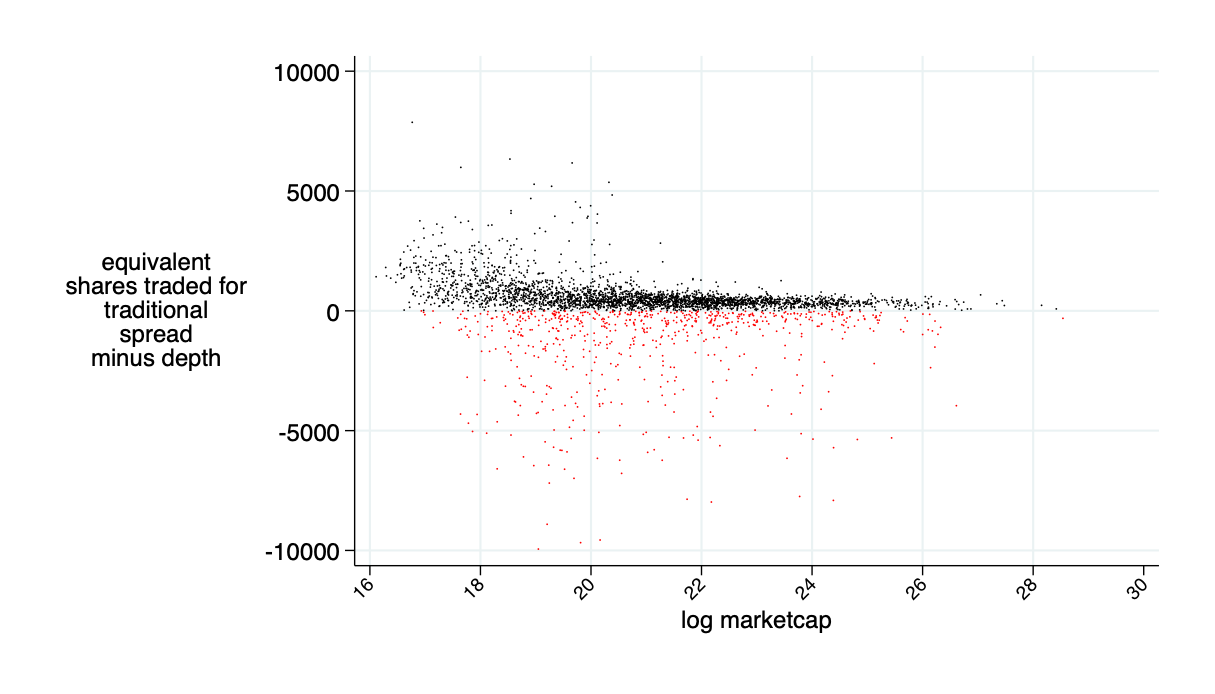
average: 94% of days AMM is better than LOB
average savings: 16 bps
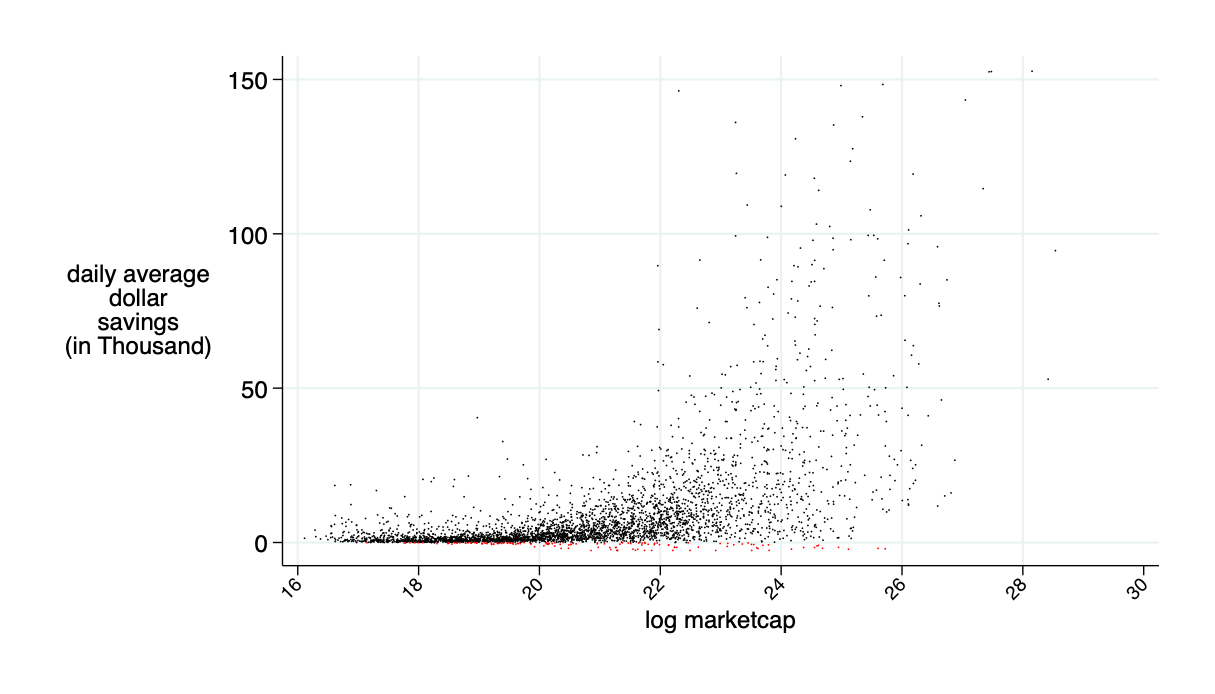
average daily: $9.5K
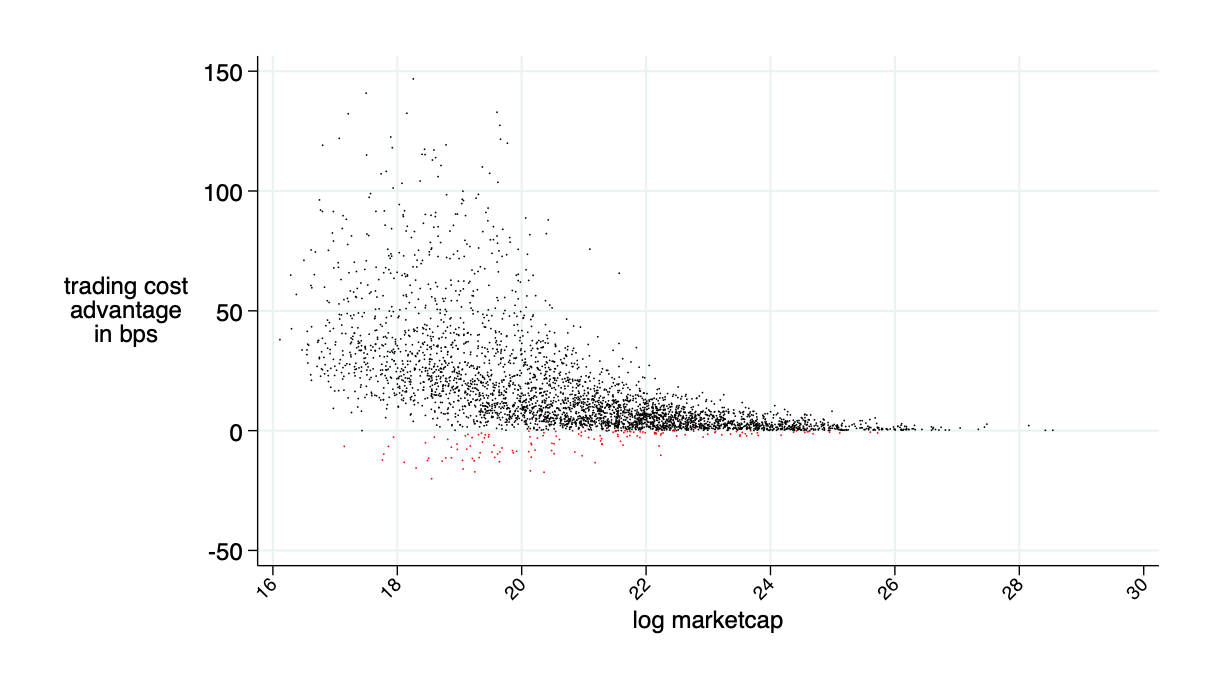
saves around 45% of transaction costs (measured in bid-ask spread)
average annual saving: $2.4 million
Summary
- AMMs do not require a blockchain - just a concept
- could be run in the existing world (though there are institutional and regulatory barriers)
- Our question:
- Can an economically viable AMM be designed for current equity markets?
- Would such an AMM improve current markets?
- Answers:
- Yes.
- Massively.
- Source of Savings:
- Liquidity providers \(\not=\) Citadel!
- \(\to\) passive liquidity provision
- \(\to\) use idle capital
- \(\to\) + better risk sharing
- pooling of liquidity
- pro-rated
- fee income
- risk
- Liquidity providers:
- use existing assets to earn passive income
- Liquidity demanders:
- predicatable price
- continuous trading
- ample liquidity
@financeUTM
andreas.park@rotman.utoronto.ca
slides.com/ap248
sites.google.com/site/parkandreas/
youtube.com/user/andreaspark2812/