Discussion of
"Liquidity Mechanisms in DeFi: Design and Fragmentation in Illiquid RWA Markets"
by Ralf Laschinger, Heiko Leonhard, Gregor Dorfleitner, and Wolfgang Schäfers
Discussant: Katya Malinova
DeGroote School of Business, McMaster University
CBER 6th Annual Conference · June 4–5, 2026
New York University, New York, NY, USA
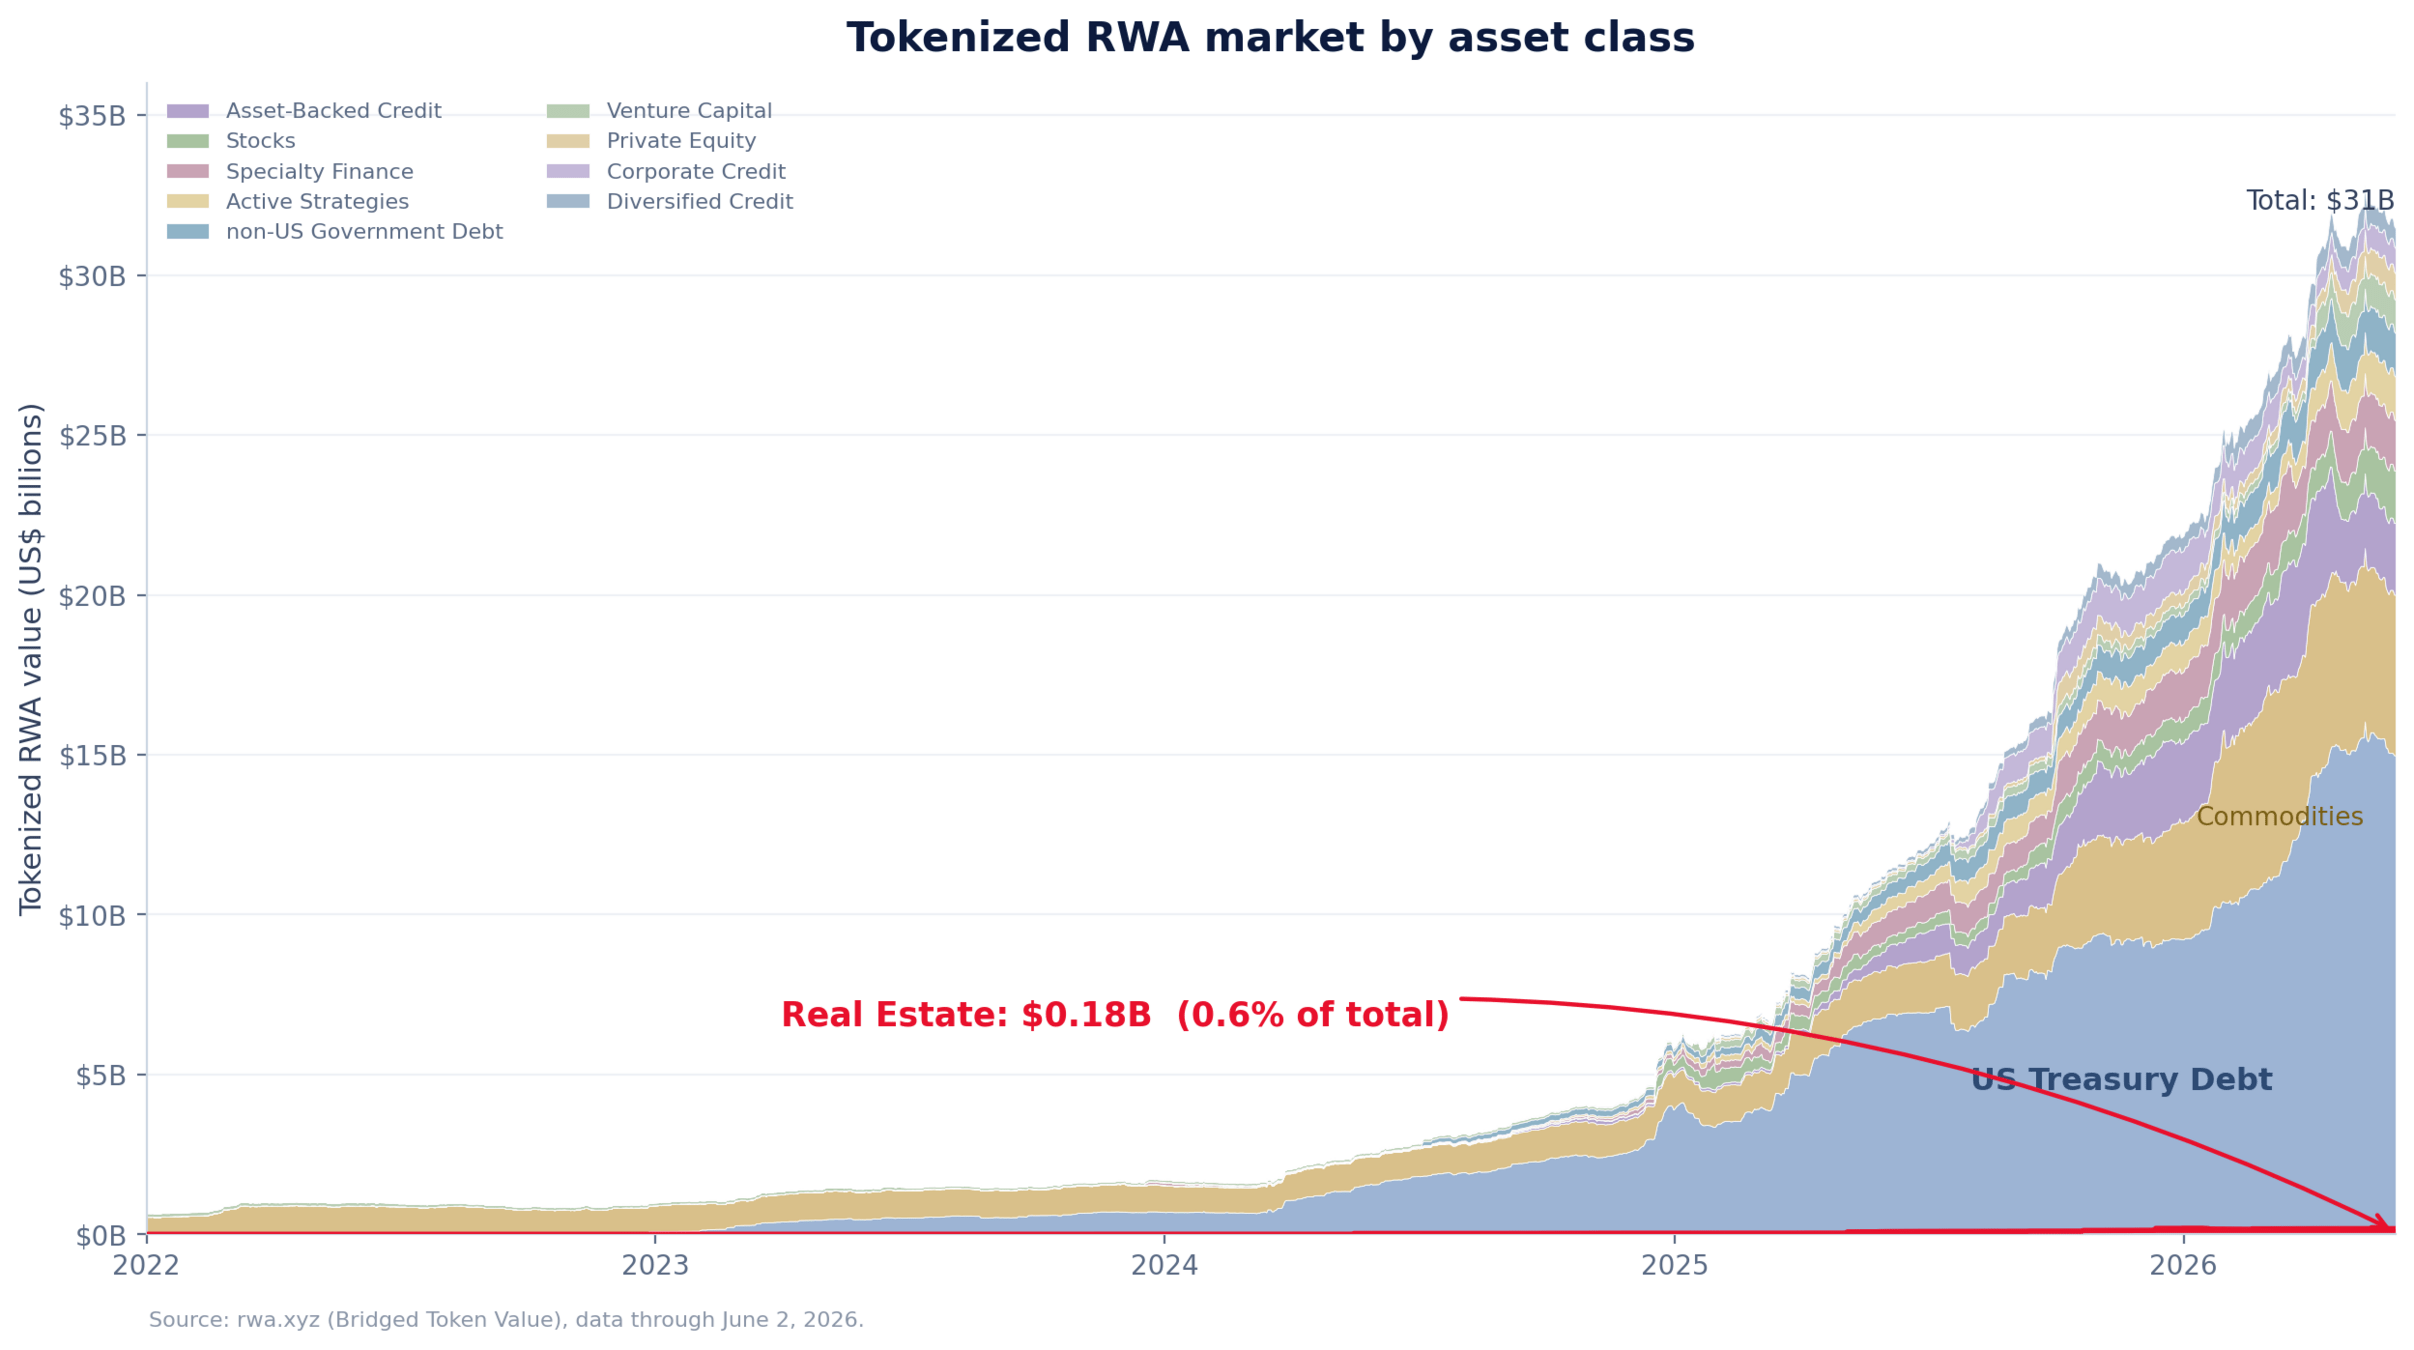
- US real estate: $55T
- REITs: $1.4T
- tokenized: ~$0
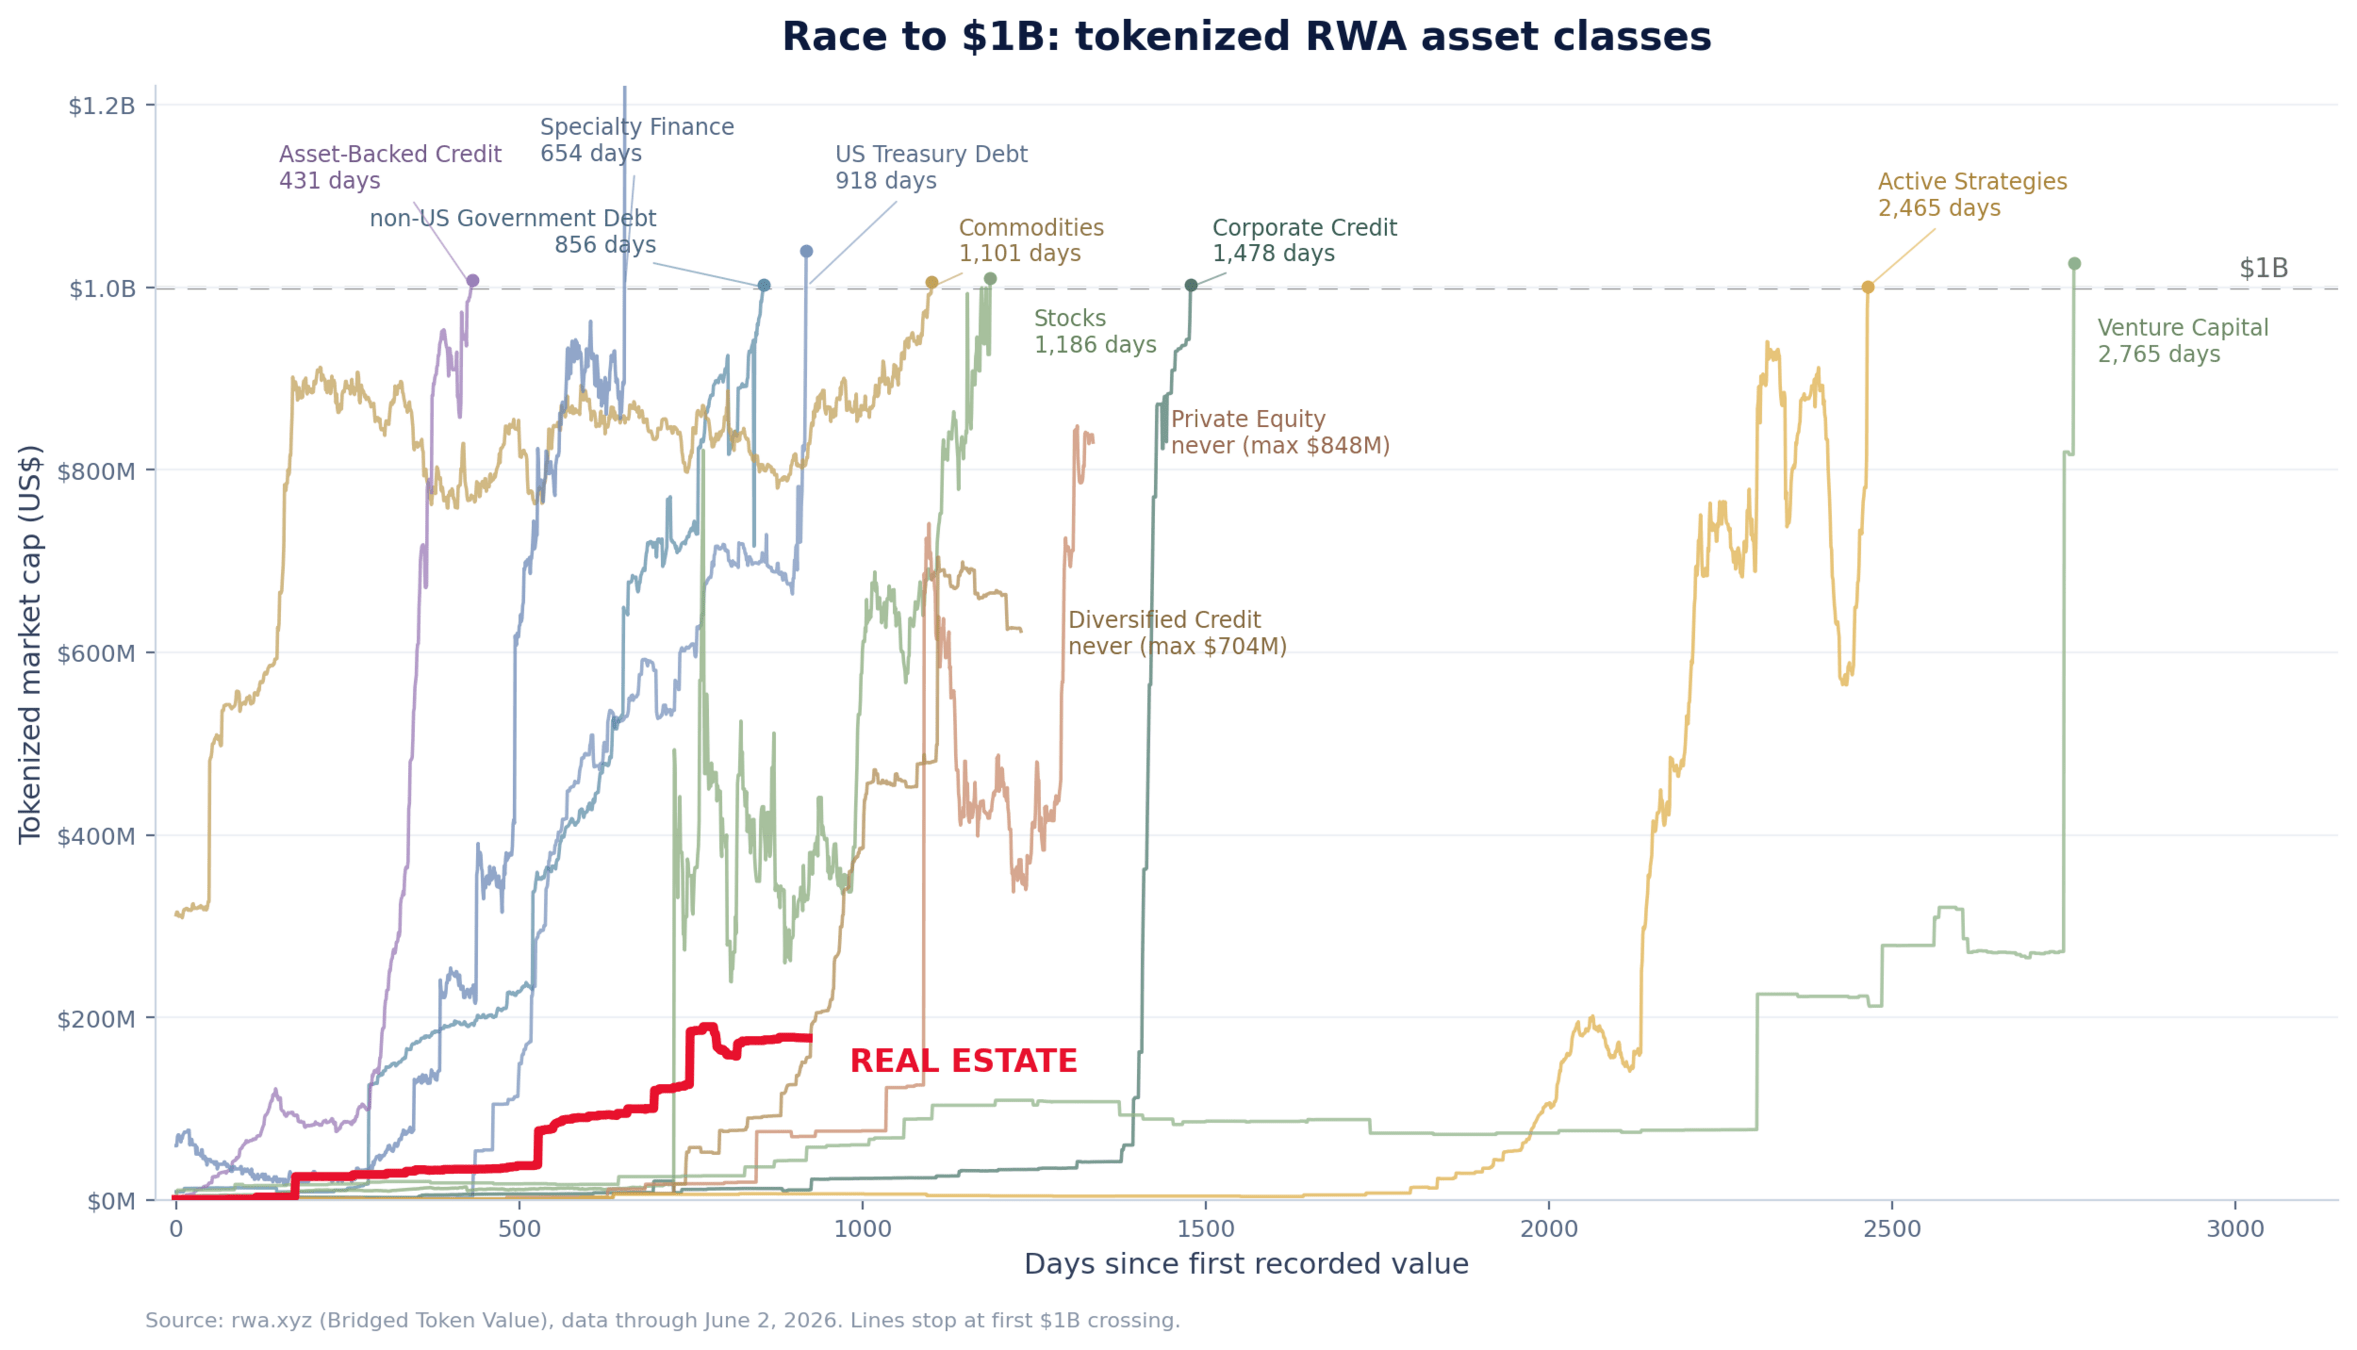
June 2, 2026 updated version of a Chainalysis blog figure
Market cap growth of tokenized RWA asset classes - to $1 Billion
Not all RWAs are created equal
… nor supposed to — Cong, Mayer & Rabetti (2026):
Different tokenization goals
Integration
already-liquid assets join the on-chain ecosystem
Enhance transferability
creating a secondary market
This paper's focus
Six-year stats:
- 752 rental properties
- ~9,200 wallets
- 777,038 trades — ≈ $50 each
- $41M — $9K per property/yr
REITs democratized access in 1960. What do tokens add (undo)?
| Problem | REIT | Property token |
| Huge lot size → fractional claims | ✓ | ✓✓ $50 of a house |
| Hard to trade, limited access → democratize access | ✓ | ✓✓ anyone*, anywhere* |
| Locked-in capital → tradability | ~ ✓ | ✓✓ 24/7 |
| Idiosyncratic risk → pooling | ✓ | ~ ✓ DIY |
| Hands-on management → professional, monitored mgmt | ✓ | ~ outsourced but who monitors? |
| Unverified valuation → audited disclosure | ✓ | ~ issuer-reported, periodic |
Transferrable? And where? AMM, P2P, or Buyback?
- Sorting?
- AMM = small, P2P = large
- LOB vs "upstairs" (blocks)
- venue pecking order: Menkveld, Yueshen & Zhu 2017 JFE (execution vs cost)
- Or: winner takes all?
- liquidity begets liquidity → one venue (Pagano 1989 QJE)
- Here: looks like one venue winning
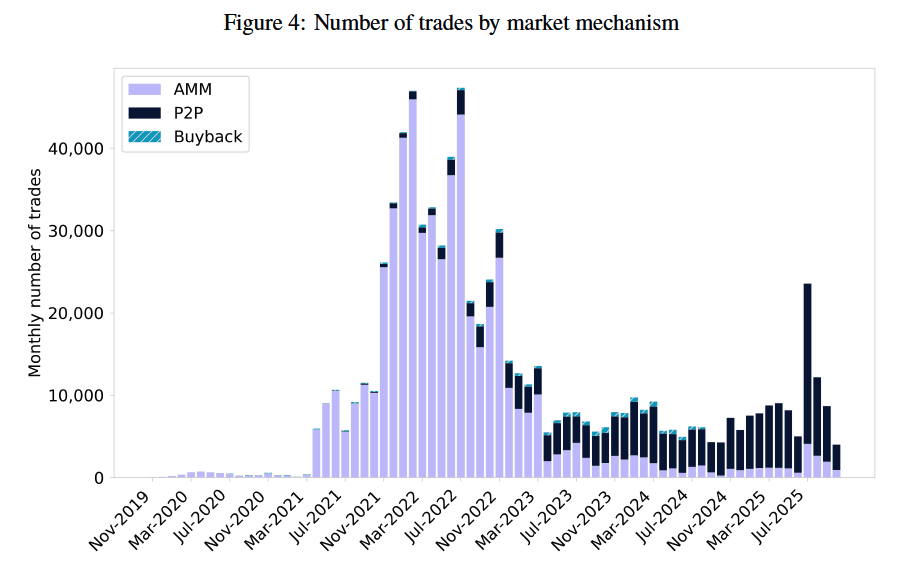
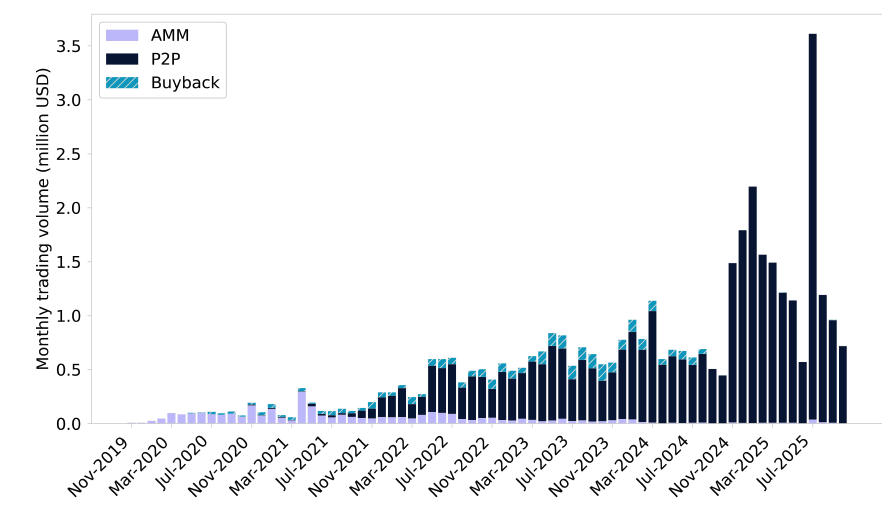
Is this bad news for AMMs? Not necessarily ...
- AMM design — active research.
- **E.g. on LP compensation (= AMM fee):
- Hasbrouck, Rivera & Saleh (MS 2026):
- ↑ fee → deeper pool → ↓ price impact → ↑ volume
- Malinova and Park 2026 "Learning from DeFi ...":
- AMM fee ∝ σ · √(q/V) — ↑ volatility, ↓ volume
- Hasbrouck, Rivera & Saleh (MS 2026):
- Here: 0.25%, hardcoded
- AMM fees not enough compensation → issuer pays incentives to LPs
- incentives stop → liquidity gone (not unique to AMM ... Park & Stinner 2026, DeFi lending)
**with apologies to the many others in this literature, many in this room
... But: is Real Estate built for 24/7 trading? (after Fig. 2 Cong, Mayer & Rabetti WP)
Asset value adjustment speed ↑
Underbuilt
Permissioned wholesale pilots on liquid assets
Integration benefits forgone
Well matched (fast)
Tokenized Treasuries, equities
Well matched (slow)
Closed-end, gated, or lock-up tokenized illiquid vehicles
Speed-mismatched - liq transformation
Real Estate!
Buy&Hold in normal times - run risk under stress (Blackstone REIT: gated withdrawals 2022–23)
corp. bond ETFs — same mismatch, but professionally managed: Koont, Ma, Pástor & Zeng, RFS 2025
Trading speed →
But: corp bonds are very liquid in a Tel-Aviv LOB (Abudy & Wohl, RoF 2018). Why?
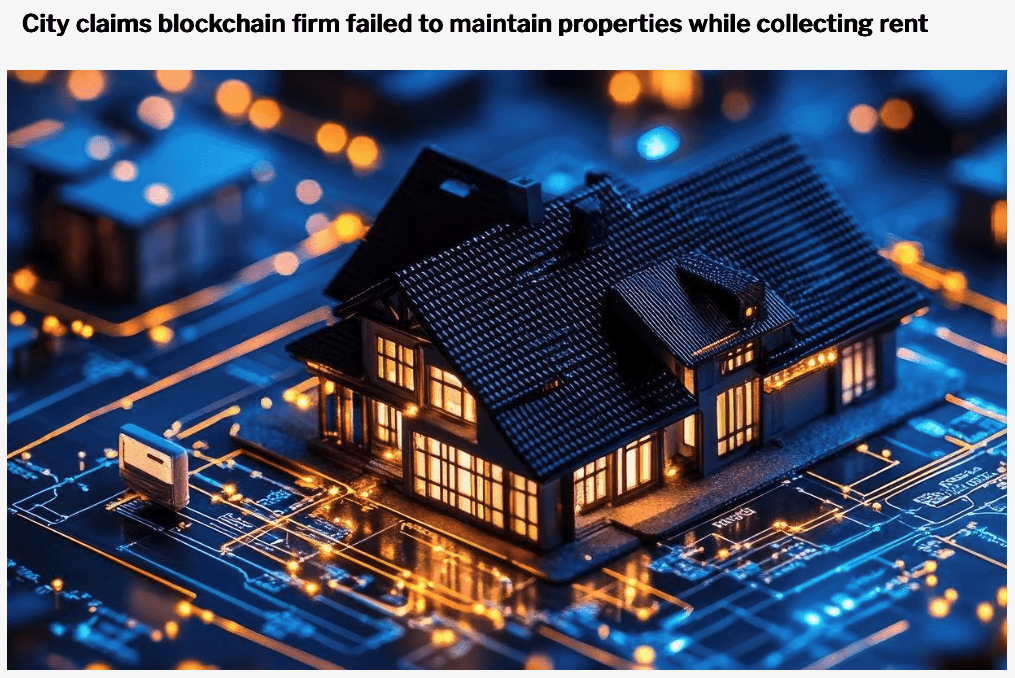
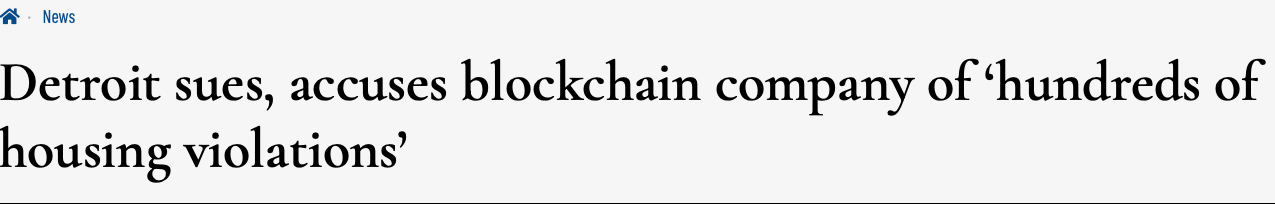
Transparent ownership, Opaque control
July 2025: TRO — rent → escrow, Buyback suspended
- Paper: "a shock to the redemption facility"
- but — also news about the asset itself!
- can we disentangle? The size split helps (?)
- spreads widen for large, narrow for small
More questions arise:
- dispersed ownership — agency problem?
- a mechanism against tokenized lemons?
Mortgage Professional America, July 7, 2025
Added ex post (web version): two papers I learned of only after the session, both directly relevant:
• Augustin, Chen, Qian & Shin (2025), From Bricks to Blocks: Tokenization and the Financialization of Real Estate
• Chemla & Tinn (2026), Digital Ownership: The Tokenization of Real-World Assets
Better rails don't automatically createreinvent
liquidity, information, nor governance.
Very nice paper.
Go read it.