
Lower Bounds for Private Estimation of
Victor Sanches Portella
July 2, 2025
joint work with Nick Harvey (UBC)

under All Reasonable Parameter Regimes
Gaussian Covariance Matrices
ime.usp.br/~victorsp
Private Covariance Estimation
Unknown Covariance Matrix
\((\varepsilon, \delta)\)-differentially private \(\mathcal{M}\) to estimate \(\Sigma\)
on \(\mathbb{R}^d\)
Goal:
Required even without privacy
Required even for \(d = 1\)
[Karwa & Vadhan '18]
Is this tight?
\((\varepsilon, \delta)\)-DP \(\mathcal{M}\) with accuracy
samples
Known algorithmic results
with
(Output of \(\mathcal{M}(X)\) does not change much if switch one \(x_i\))
Our Results - New Lower Bounds
Theorem
For any \((\varepsilon, \delta)\)-DP algorithm \(\mathcal{M}\) such that
and
we have
Above 1/n, DP may not be meaningful
Previous
Lower Bounds
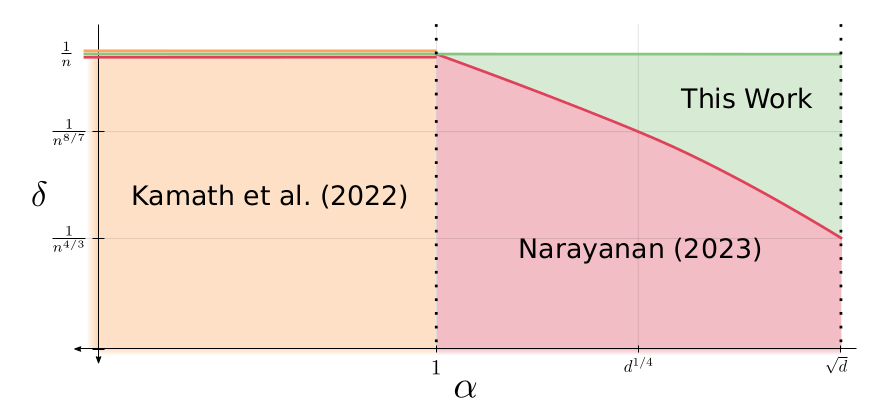
Accuracy \(\alpha^2\)
New Fingerprinting Lemma using
Stokes' Theorem
Follow up:
LBs for other problems
[Lyu & Talwar ´25]
Lower Bounds via Fingerprinting
Measures correlation between and
Correlation statistic
If \(z \sim \mathcal{N}(0, \Sigma)\) indep. of \(X\)
small
If \(\mathcal{M}\) is accurate
large
Fingerprinting Lemma
Approx. equal by privacy
Approx. equal by privacy
Example:
Randomizing \(\Sigma\)
To get a FP lemma, we need to randomize \(\Sigma\)
How to choose the distribution of \(\Sigma\)?
Narayanan (2023) drops independence with a Bayesian argument
otherwise, there is \(\mathcal{M}\) that knows \(\Sigma\) and ignores \(X\)
Most FP Lemma take independent coordinates
1 dim. FP Lemma and apply to each coord.
For covariance works only for high-accuracy \(\mathcal{M}\) (Kamath et al. 2022)
Our idea: Many FP Lemmas use Stein's identity (Integration by parts)
How to do something similar in high-dimensions?
Score Statistic
Gaussian Score function
Score Attack Statistic
First step: Pick a different correlation statistic
"Usual" choice
[Cai et al. 2023]
New Fingerprinting Lemma
\(\Sigma \sim\) Wishart leads to elegant analysis
Stein-Haff Identity
Want to "Move the derivative" with integration by parts
Stokes' Theorem
Divergence of \(\Sigma \mapsto \mathbb{E}[\mathcal{M}(X) \; | \; \Sigma]\)
Large If \(\mathbb{E}[\mathcal{M}(X) \; | \; \Sigma]\approx \Sigma\)
Main property:
\(\Sigma\) is random with density \(p\)
Summary
Our results
Score Attack Statistic
Tight lower bounds private covariance estimation
over a broad parameter regime
Stein-Haff Identify
Thanks!
Technical Secret Sauce:
New Fingerprinting Lemma