Efficient and Optimal Fixed-Time Regret with Two Experts
Laura Greenstreet, Nick Harvey, Victor Sanches Portella

The Two-Experts' Problem
Prediction with Expert Advice
Player
Adversary
\(n\) Experts
\displaystyle
\mathrm{Regret}(T) = \sum_{t = 1}^T \langle \ell_t, x_t \rangle - \min_{i = 1, \dotsc, n} \sum_{t = 1}^T
\ell_t(i)
0.5
0.1
0.3
0.1
Probabilities
x_t
1
0
0.5
0.3
Costs
\ell_t
Player's loss:
\langle \ell_t, x_t \rangle
Loss of Best Expert
Player's Loss
Knows \(T\) (fixed-time)
Known and New Results
Multiplicative Weights Update method:
\displaystyle
\mathrm{Regret}(T) \leq \sqrt{\frac{T}{2} \ln n}
Optimal for \(n,T \to \infty\) !
If \(n\) is fixed, we can do better
Worst-case regret for 2 experts:
Cover's Algorithm
\(O(T)\) time per round
Dynamic Programming
\(\{0,1\}\) costs
\(O(1)\) time per round
Stochastic Calculus
\([0,1]\) costs
\displaystyle \sqrt{\frac{T}{2\pi}} + O(1)
[Cover '67]
Our Algorithm
Technique:
Discretize a solution to a stochastic calculus problem
[HLPR - FOCS '20]
How to exploit the knowledge of \(T\)?
We need to analyze the discretization error!
!
!
Online Learning
🤝
Stochastic Calculus
Gaps and Cover's Algorithm
Simplifying Assumptions
We will look only at \(\{0,1\}\) costs
1
0
0
1
0
0
1
1
Equal costs do not affect the regret
Cover's algorithm relies on these assumptions by construction
Our alg. and analysis extends to fractional costs
Gap between experts
Thought experiment: how much probability mass to put on each expert?
Cumulative Loss on round \(t\)
\(\frac{1}{2}\) is both cases seems reasonable!
Takeaway: player's decision may depend only on the gap between experts's losses
Gap = |42 - 20| = 22
Worst Expert
Best Expert
42
20
2
2
42
42
(and maybe on \(t\))
Cover's Dynamic Program
Player strategy based on gaps:
Choice doesn't depend on the specific past costs
p(t, g)
on the Worst expert
1 - p(t, g)
on the Best expert
We can compute \(V^*\) backwards in time via DP!
\displaystyle
V^*[t, g] =
Max regret to be suffered at time \(t\) with gap \(g\)
\(O(T^2)\) time to compute \(V^*\)
At round \(t\) with gap \(g\)
\displaystyle
V^*[0, 0] =
Max. regret for a game with \(T\) rounds
Computing the optimal strategy \(p^*\) from \(V^*\) is easy!
Cover's DP Table
(w/ player playing optimally)
Continuous Regret
A Probabilistic View of Regret Bounds
Formula for the regret based on the gaps
\displaystyle
\mathrm{Regret(T)}
= \sum_{t = 1}^{T}
p(t, g_{t-1})(g_t - g_{t-1})
Discrete stochastic integral
Moving to continuous time:

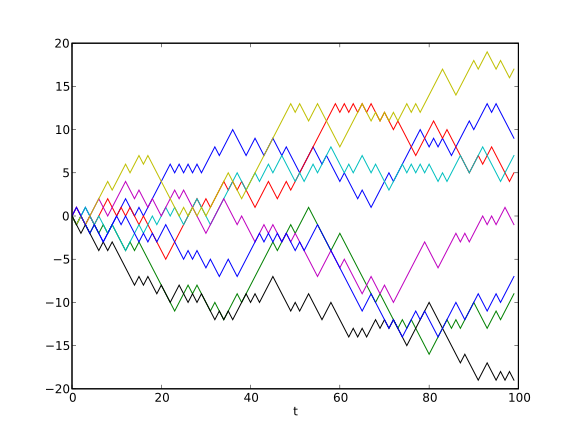
Random walk \(\longrightarrow\) Brownian Motion
\(g_0, \dotsc, g_t\) are a realization of a random walk
\displaystyle
\Bigg\{
\displaystyle
\Delta g_t = \pm 1
Useful Perspective:
Deterministic bound = Bound with probability 1
A Probabilistic View of Regret Bounds
Formula for the regret based on the gaps
\displaystyle
\mathrm{Regret(T)}
= \sum_{t = 1}^{T}
p(t, g_{t-1})(g_t - g_{t-1})
Random walk \(\longrightarrow\) Brownian Motion
\displaystyle
\mathrm{ContRegret(p, T)}
= \int_{0}^{T}
p(t, |B_t|)\mathrm{d}|B_t|
Reflected Brownian motion (gaps)
Conditions on the continuous player \(p\)
Continuous on \([0,T) \times \mathbb{R}\)
p(t,0) = \frac{1}{2}
for all \(t \geq 0\)
Stochastic Integrals and Itô's Formula
How to work with stochastic integrals?
\displaystyle
R(T, |B_T|) - R(0, 0) =
Itô's Formula:
\(\overset{*}{\Delta} R(t, g) = 0\) everywhere
ContRegret \( = R(T, |B_T|) - R(0,0)\)
\displaystyle
\implies
Goal:
Find a "potential function" \(R\) such that
(1) \(\partial_g R\) is a valid continuous player
(2) \(R\) satisfies the Backwards Heat Equation
\displaystyle
+ \int_{0}^T \overset{*}{\Delta} R(t, |B_t|) \mathrm{d}t
Different from classic FTC!
\displaystyle
\mathrm{ContRegret}(\;\;\;\;\;\;, T)
\displaystyle
\partial_g R
\;\;\; \vphantom{\overset{*}{\Delta}} R = \;\;\;R + \;\;\;\;\;\;\; R
\displaystyle
\partial_t
\displaystyle
\tfrac{1}{2}\partial_{gg}
\displaystyle
\overset{*}{\Delta}
Backwards Heat Equation
Stochastic Integrals and Itô's Formula
\displaystyle
R(T, |B_T|) - R(0, 0) =
Goal:
Find a "potential function" \(R\) such that
(1) \(\partial_g R\) is a valid continuous player
(2) \(R\) satisfies the Backwards Heat Equation
\displaystyle
\mathrm{ContRegret}(\;\;\;\;\;\;, T)
\displaystyle
\partial_g R
How to find a good \(R\)?
?
Suffices to find a player \(p\) satisfying the BHE
p(t,g) = \mathbb{P}(\mathcal{N}(0, T - t) > g)
\(\approx\) Cover's solution!
Also a solution to an ODE
\displaystyle R(T, |B_T|) - R(0,0) \leq \sqrt{\frac{T}{2\pi}}
R(t,g) \approx \int p(t,g)
Then setting
preserves BHE and
p = \partial_g R
Discretization
Discrete Itô's Formula
\displaystyle
R(T, |B_T|) - R(0, 0) = \displaystyle
\mathrm{ContRegret}(\partial_g R, T) + \int_{0}^T \overset{*}{\Delta} R(t, |B_t|) \mathrm{d}t
\displaystyle
R(T, g_T) - R(0, 0) =\;\;\; \mathrm{Regret}(R_g, T)
How to analyze a discrete algorithm coming from stochastic calculus?
Discrete Itô's Formula!
\displaystyle
+ \sum_{t = 1}^T \Big(R_t(t, g_t) + \frac{1}{2} R_{gg}(t, g_t)\Big)
Discrete Derivatives
Surprisingly, we can analyze Cover's algorithm with discrete Itô's formula
Itô's Formula
Discrete Itô's Formula
Discrete Algorithms
p^*(t,g)
= V_g^*[t,g]
V_t^*[t, g] + \frac{1}{2} V_{gg}^*[t,g] = 0
\(V^*\) satisfies the "discrete" Backwards Heat Equation!
Not Efficient
Efficient
Discrete Itô \(\implies\)
Regret of \(p^* \leq V^*[0,0]\)
BHE = Optimal?
Hopefully, \(R\) satisfies the discrete BHE
Discretized player:
R_g(t,g)
We show the total is \(\leq 1\)
Cover's strategy
Our Results
An Efficient and Optimal Algorithm in Fixed-Time with Two Experts
Technique:
Solve an analogous continuous-time problem, and discretize it
[HLPR '20]
How to exploit the knowledge of \(T\)?
Discretization error needs to be analyzed carefully.
BHE seems to play a role in other problems in OL as well!
Solution based on Cover's alg
Or inverting time in an ODE!
We show \(\leq 1\)
\(V^*\) and \(p^*\) satisfy the discrete BHE!
Insight:
Cover's algorithm has connections to stochastic calculus!
Questions?
ALT 2022 - Two Experts
By Victor Sanches Portella